Key Points:
- A plumbing insurance claim for outdoor water line damage depends on proving the leak was sudden, accidental, and tied to covered property damage.
- Homeowners should document photos, plumber reports, receipts, timelines, and maintenance records.
- Outdoor pipes, pools, lawns, and repairs may need separate policy review.
A plumbing insurance claim after outdoor water line damage can be covered when the loss is sudden and accidental. However, insurers often push back if the damage looks gradual or maintenance-related.
New York homeowners must separate three issues early. These are the damaged pipe, resulting water damage claims, and outdoor features like pools or lawns. Here are the seven critical questions you need answered.
1. Can a plumbing insurance claim cover outdoor water line damage?
A plumbing insurance claim can cover resulting water damage when a pipe failure was sudden and accidental. The repair to the pipe itself may be treated differently from the damage caused by the water. Many policies separate the failed part from the walls, flooring, contents, or structural areas affected after the break.
Outdoor service lines, underground piping, irrigation lines, and pool plumbing need closer review. Some claims depend on endorsements, common denial mistakes, and whether the damaged item is part of the insured structure.
2. Why do insurers deny insurance claims for plumbing after yard leaks?
Insurance companies scrutinize yard leaks closely before paying out. They look for reasons to classify the issue as a long-term maintenance problem rather than an accident. This happens often when filing insurance claims for plumbing issues that start underground. Insurers regularly use specific policy exclusions to deny these files.
| Insurer concern | What it means | Proof that may help |
|---|---|---|
| Gradual leak | Water escaped over time | Plumber report, meter records |
| Wear and tear | Pipe failed from age | Cause of loss photos, parts |
| Excluded property | Damage stayed in yard | Policy language review |
3. What records prove the damage was sudden, not long-term?
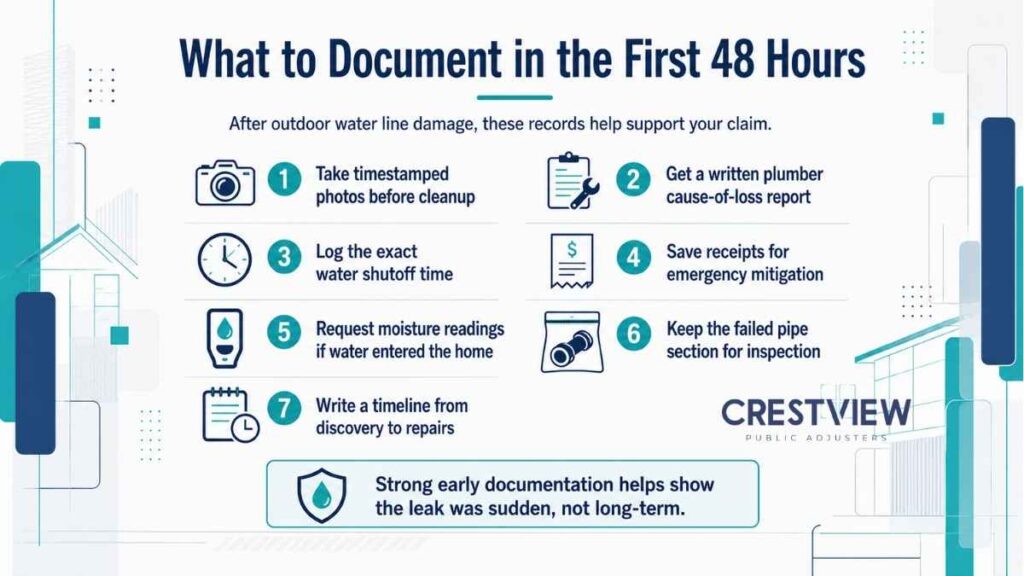
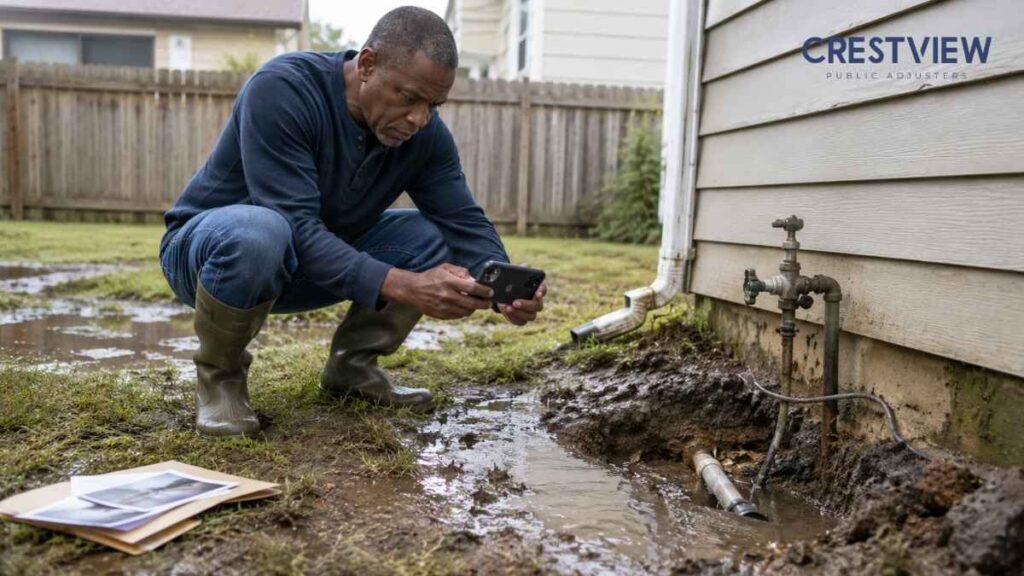
Proving a leak happened quickly prevents a fast denial. The New York State Department of Financial Services (DFS) advises homeowners to document losses before cleanup, keep receipts, and avoid permanent repairs before an insurer inspection. Gathering evidence in the first 48 hours protects your file.
- Take timestamped photos of pooling water before starting cleanup.
- Obtain a written cause-of-loss report from your plumber.
- Log the exact water shutoff time to establish a timeline.
- Keep receipts for emergency mitigation and temporary repairs.
- Request contractor moisture readings if water entered the home.
- Save the failed pipe section in a labeled bag.
- Write a timeline from discovery to mitigation.
4. Which plumbing checks in hot weather help support maintenance history?
Regular maintenance records show your insurer that you care for your property. Performing plumbing checks in hot weather helps establish this history before a crisis occurs. During hot New York summers, check hose bibs, irrigation lines, pool lines, and exterior shutoff valves. Save your pool service invoices and irrigation repair receipts.
What proof helps a plumbing insurance claim after a hot-weather leak?
- A meter reading taken before and after the water shutoff.
- A plumber’s note stating the cause of the line failure.
- Photos showing if water reached walls, flooring, or foundations.
Outdoor leaks turn into policy disputes when the first report uses weak wording or missing dates. At Crestview, we review the damage, the policy, and the early claim file before you respond to a low estimate. Get professional public adjuster advice early. Call our team before giving a recorded statement.
5. Does homeowners insurance cover pool-line leaks or pool damage?
A pool supply line leak is handled differently from a broken indoor pipe. Damage to your home from escaped water requires a separate review from damage to the pool structure, deck, yard, or patio. To protect your claim, maintain regular records using smart pool maintenance tips.
Useful pool maintenance tips for claim files:
- Keep professional pool opening and closing invoices.
- Save written pressure-test results from your service company.
- Photograph pool equipment before and after repairs.
- Keep the failed line or fitting for inspection.
6. What water damage prevention steps help before there is a claim?
Active water damage prevention serves as excellent evidence during a claim dispute. According to the Environmental Protection Agency (EPA) WaterSense program, the average household leak wastes more than 9,300 gallons of water per year.
A quick meter check during a no-use period reveals hidden underground leaks before they cause major property damage. Track these tips to maximize your payout using a simple seasonal checklist. Keeping short, dated records proves you were not negligent.
Seasonal checklist actions:
- Spring: open exterior supply lines and inspect hose bibs.
- Summer: check irrigation zones and pool refill lines.
- Fall: close and drain seasonal outdoor lines.
- After storms: photograph pooled water near foundation areas.
7. What backyard water safety details should New York homeowners document?
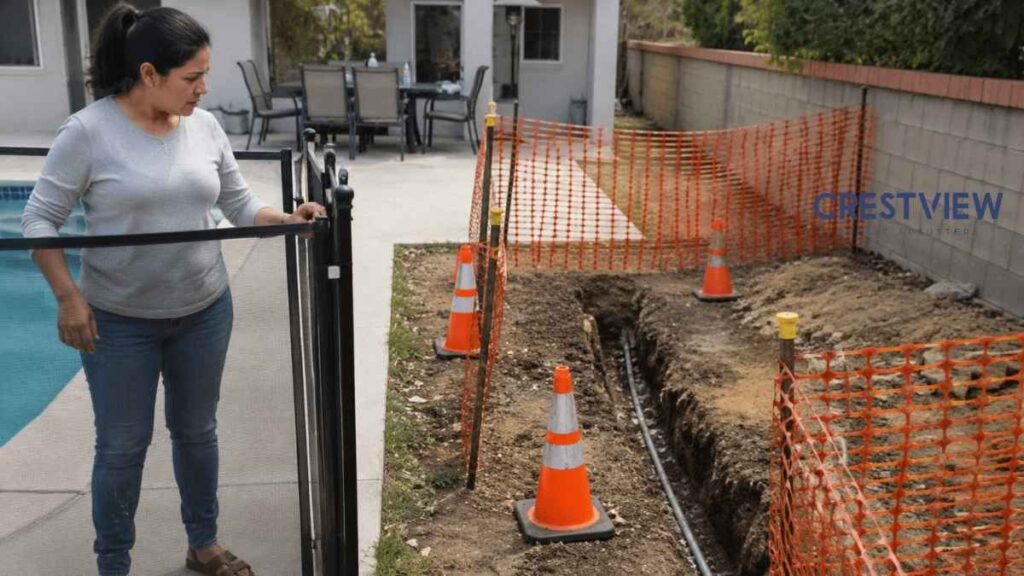
When an underground pipe bursts, excavation can disrupt your entire yard. This introduces important backyard water safety issues that impact your insurance profile. New York State pool rules require secure barriers for any swimming pool holding water deeper than 24 inches, with permanent barriers at least 48 inches high.
Your claim file must separate safety compliance photos from property damage photos. Photograph gates, pool alarms, electrical equipment, exposed trenches, temporary barriers, and warning tape after excavation. These safety records do not prove coverage, but they reduce side disputes regarding neglect after outdoor water line repairs.
8. When should you call a public adjuster for an outdoor plumbing claim?
Contact a public adjuster before signing a final release, accepting a low settlement estimate, or allowing contractors to discard damaged parts. Call immediately if your insurer mentions terms like wear and tear, seepage, lack of maintenance, or outdoor property exclusions. An adjuster assists you with detailed property inventories, policy coverage reviews, repair cost assessments, and direct settlement negotiations.
FAQs About Plumbing Insurance Claim Coverage in New York
Can I repair the broken outdoor pipe before the insurance inspection?
Yes, but limit repairs to emergency work needed to stop damage. Photograph everything first, save receipts, keep the failed part, and ask the insurer what documentation they require before making permanent repairs.
Will insurance pay for the broken pipe itself?
Sometimes the water damage is covered, while the pipe repair is not. The answer depends on the cause, policy wording, endorsements, and whether the pipe failed suddenly or from wear, age, roots, or corrosion.
Should I file a claim if the water stayed outside?
Review the policy before filing. If damage stayed in the yard, pool, patio, or landscaping, coverage may be limited. If water entered the home or affected structural foundations, the claim needs closer review.
Speak With a New York Claim Expert Before the File Gets Framed
Outdoor plumbing damage can look simple at first, but the wording in your first claim report shapes the entire file. A clear timeline, a detailed plumber report, an organized photo set, and an expert policy review show exactly what failed, when it failed, and what damage followed.
At Crestview Public Adjusters, we help homeowners, property owners, and business owners across New York review water damage and plumbing-related claims. Call our team at (551) 316-7204 or send your claim details through the website, and our team will review the file before you proceed with the next step.